Priced by the Point: How Your Address Became Your Interest Rate
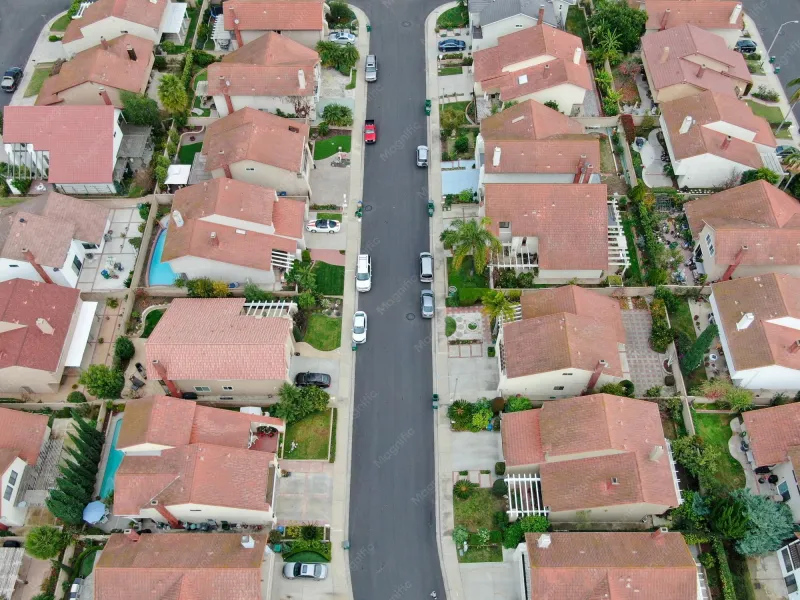
Photo: aerial view of suburban houses divided neighborhood inequality, via img.freepik.com
Two households, identical credit scores, identical claims histories, identical cars. One pays $2,300 a year for auto insurance. The other pays $3,900. The difference between them is eight miles of asphalt in metropolitan Detroit.
This is not an anomaly. It is the design of modern risk scoring, and it is built — layer by layer — on geography.
The Geometry of Price
Location-based pricing predates the algorithm. Insurers have weighted territory since the actuarial tables of the nineteenth century, and mortgage underwriters have always priced the property alongside the borrower. What has changed is resolution. Where an underwriter once assessed a zip code, today's models score the census block group, the traffic grid, the crime-incident density, and increasingly, the satellite-derived characteristics of the roof over your head.
Geospatial data has made this granular pricing possible at scale. Vehicle telematics reveals where a car is actually driven. Property analytics platforms score every parcel in the country on wildfire exposure, flood zone drift, and even vegetation clearance. Credit models incorporate public records that are themselves indexed by address. The result is a price that follows the map with extraordinary precision — and, critics argue, with troubling consequences.
Mapping the Disparity
When researchers overlay premium data on demographic layers, a pattern emerges that is difficult to dismiss as coincidence. A widely cited 2017 analysis by the Consumer Federation of Union of Concerned Scientists found that predominantly non-white neighborhoods in several major metros paid higher auto insurance premiums than predominantly white neighborhoods with comparable accident costs. ProPublica's investigation of homeowner's insurance reached similar conclusions in Chicago, Dallas, and Atlanta.
The mechanism is not necessarily discriminatory intent. Insurers point to legitimate spatial variables: theft rates, litigation environments, road conditions, weather exposure. But when you aggregate enough location-based factors, the composite score begins to function as a proxy for race and income — a phenomenon data scientists call "digital steering."
Lending faces the same critique. Studies of algorithmic underwriting have found that fintech lenders, despite using less demographic data than traditional banks, nonetheless produced rate disparities by race in some analyses — because geographic and behavioral proxies recovered the very information that was excluded.
Redlining by Another Name?
The comparison to redlining is not rhetorical decoration. The HOLC maps of the 1930s graded neighborhoods, and those grades suppressed investment for generations. Modern geospatial scoring does not draw lines on a map; it embeds them in a model. The effect can be similar: capital flows away from certain places, prices rise there, and the geography of disadvantage compounds.
Defenders of the practice raise a fair counterpoint. Risk genuinely varies by location. A home in a wildfire corridor is more expensive to insure, and pretending otherwise simply redistributes cost. The question is not whether geography should inform pricing, but which geographic variables are legitimate, and whether the feedback loop — where high prices in a neighborhood depress investment, which worsens the risk profile, which raises prices further — is being measured and managed.
The Regulatory Map Is Catching Up
Colorado has enacted the nation's most explicit restrictions, barring insurers from using many location-based factors without demonstrating that they derive from actual risk. The FTC and CFPB have both signaled scrutiny of algorithmic pricing under fair-lending and unfair-practice authorities. Several states now require insurers to justify territorial rating factors.
For the geospatial profession, the moment is uncomfortable but clarifying. Location intelligence is a powerful analytical tool, and its use in pricing is neither inherently good nor inherently bad. But the industry's own history — the HOLC maps were once considered objective, data-driven assessments too — argues for humility. Every layer added to a pricing model is a choice. Every proxy has a shadow.
The map, in other words, is never neutral. The only question is who draws it, and whether anyone is checking the lines.